How to Set Up a Wireless Credit Card Terminal: Step-by-Step Guide
How to Set Up a Wireless Credit Card Terminal: Step-by-Step Guide
A wireless credit card terminal lets your business take card payments wherever the sale happens: a customer’s driveway, a farmers market stall, a delivery stop, or the far end of a warehouse. This guide shows you how to set up a wireless credit card terminal step by step, from choosing between Wi-Fi and cellular to running your first test sale and training your team.
Running a field team? If your technicians, drivers, or crews take payments at customer locations, setup looks a little different than it does for a shop with a counter and steady Wi-Fi. Every device needs a connection that works on site, a person who is responsible for it, and an end-of-day routine so the office can match payments to jobs. We call out those field-team details throughout this guide. If you are still choosing hardware for a contracting business, start with our checklist on wireless credit card terminals for Wisconsin contractors, then come back here to set it up. For the bigger picture of payments in the trades, including deposits and ACH, see our home services payment processing guide.
What Is a Wireless Credit Card Terminal?
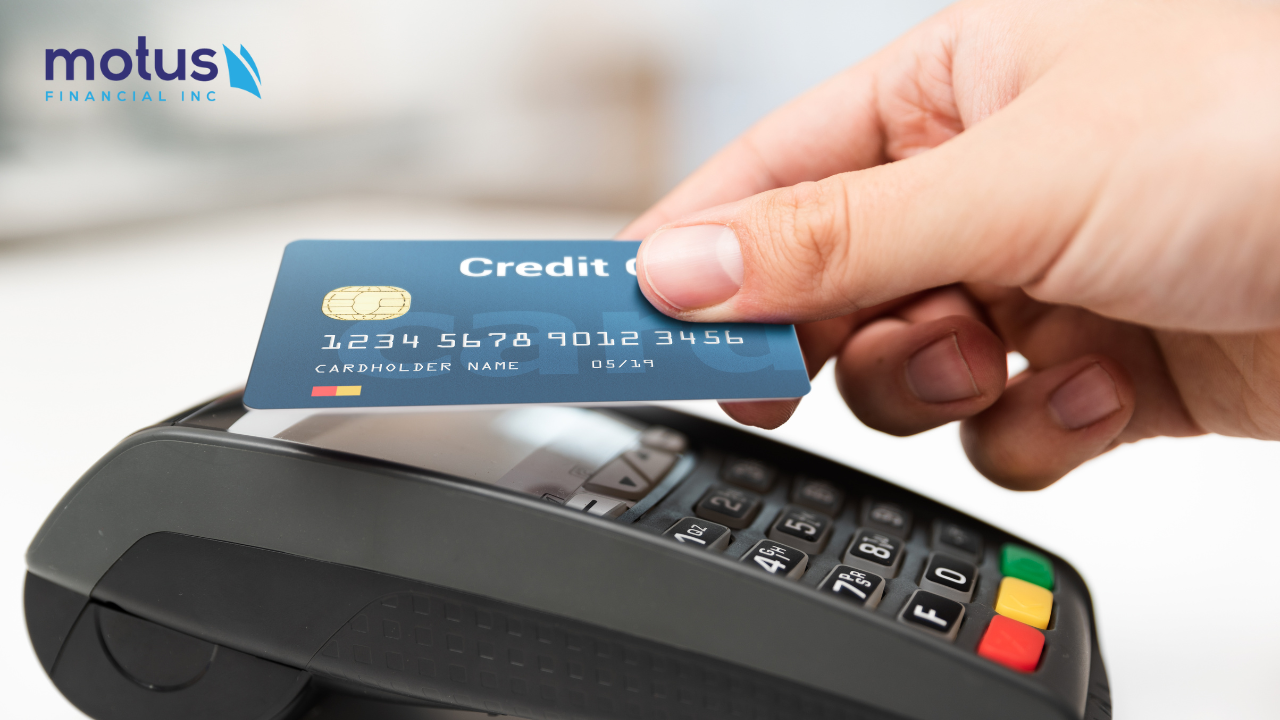
A wireless credit card terminal is a portable device that takes credit and debit card payments without a phone line or network cable. Depending on the model, it gets online in one of three ways:
- Wi-Fi: the terminal joins a wireless network, such as your shop or office network.
- Cellular: the terminal has its own mobile data connection, usually through a SIM card, so it works wherever the carrier has coverage.
- Phone pairing: a smaller card reader connects to an app on a smartphone or tablet, usually over Bluetooth, and uses that device’s connection.
Some terminals support more than one option, such as Wi-Fi with cellular as a backup. Most current models read chip cards, contactless tap payments, and mobile wallets. If a phone-based reader sounds like a better fit for your team, our page on mobile credit card acceptance covers those options.
Why Businesses Use Wireless Terminals
A wireless terminal moves checkout to wherever your customer is. Businesses use them to:
- Get paid where the work happens, not only at a register.
- Close out a job or order on the spot instead of sending a bill and waiting.
- Keep card numbers off paper, because the card is tapped or inserted instead of written on a work order.
- Shorten lines at events, on patios, and at busy counters.
If most of your payments happen at one fixed counter, our guide to setting up a countertop payment terminal may be a better match.
Wi-Fi vs. Cellular: How Each Works Day to Day
The biggest setup decision is how the terminal gets online. Here is how the two main options compare in daily use.
| Workflow | Wi-Fi Terminal | Cellular Terminal |
|---|---|---|
| Where it works best | Shops, offices, restaurants, and venues with a network you control | Job sites, deliveries, outdoor events, and rural routes |
| Getting connected each day | Reconnects to a saved network, but needs a new network at each new location | Connects on its own wherever the carrier has signal |
| Setup step | Enter the network name and password on the device | Install or activate the SIM card, with no network login needed |
| Ongoing cost | Uses your existing internet service | May involve a data plan, so ask whether it is included or billed separately |
| Common weak spots | Guest networks with a sign-in page and weak signal at the edge of a building | Basements, mechanical rooms, metal buildings, and carrier coverage gaps |
| Fit for field teams | Works only if every stop has a usable network or the technician runs a phone hotspot | Usually the more practical choice for crews on the road |
For a field team, the real question is what the technician does when they arrive. With a cellular terminal, they turn it on and take the payment. With Wi-Fi, they need a network at every stop, which usually means asking the customer for a password or running a hotspot from a phone. If you lean toward cellular, find out whose network the device runs on and look at a coverage map for the counties you work in, especially across northern or central Wisconsin.
Questions to Ask Before You Choose Hardware
Terminal models change often, so instead of recommending one device, here are the questions worth asking any provider before you buy:
- Will it work with my merchant account? Some terminals are locked to one processor, so check before you buy or reuse a device.
- How does it connect? Wi-Fi, cellular, phone pairing, or a combination, and who supplies the SIM card and data plan.
- Which payments does it accept? Look for tap, chip, and mobile wallets, with swipe as a backup.
- How are receipts handled? Printed, sent by text or email, or both.
- Is there an offline mode? If so, ask what its limits are and how you learn about a later decline.
- Will the battery last a full shift? Ask what charging options come with it.
- Can each employee have their own login? And can reports be filtered by user and by day.
- Does it need to talk to other software? Such as your POS, invoicing, or field-service system.
- Who do I call when it stops working? And how fast does a replacement arrive.
For contractors and home-service crews, our buying checklist for contractor terminals goes deeper on offline payments, deposits, multi-tech reporting, and Wisconsin weather.
How to Set Up a Wireless Credit Card Terminal: Step by Step
Once you have chosen a terminal, setup is straightforward. Here is the process from unboxing to your first real sale.
1. Choose the Right Terminal for How You Work
Match the connection to where you take payments: Wi-Fi for locations with a network you control, cellular for job sites and the road, or a terminal that supports both if you do a mix. Run through the hardware questions above before you order, and if you have a field team, decide up front which employee will carry each device.
2. Open or Confirm Your Merchant Account
You need a merchant account before the terminal can take payments. It is what moves money from your customer’s card to your business bank account. If you already process with Motus Financial, tell us which terminal you are adding so we can set it up for your account. If your office also takes payments by phone, mail, or invoice, ask us about adding a virtual terminal at the same time.
3. Charge and Connect the Hardware
- Charge the battery fully before first use, and keep the charger with the device.
- Cellular terminals: install the SIM card if it is not already in place, power on, and confirm the signal indicator shows a connection.
- Wi-Fi terminals: connect to a secured network you control. Public or guest networks that require a sign-in page often will not work for a terminal.
- Receipt paper: if the terminal has a built-in printer, load the paper roll the way the manufacturer’s instructions show.
- Field teams: label each device and write down its serial number and the employee it is assigned to.
4. Configure the Terminal Settings
Depending on the terminal, some settings are loaded by your processor and others are set on the device. Check each of these:
- Language, date, and time: Wisconsin is on Central Time, and an incorrect clock makes reports harder to read.
- Transaction options: tipping, sales tax, and receipt preferences.
- User access: a login for each employee, with refunds and voids limited to a manager where the terminal allows it.
5. Activate the Terminal With Your Processor
Before the terminal can approve a sale, it has to be linked to your merchant account. Depending on the terminal and processor, this may happen remotely when the device first connects, or you may need to enter merchant details that we provide. Our team can walk you through this step so you are not guessing at settings.
6. Run Test Transactions
Run a few small test sales with a chip card, a tap card, and a mobile wallet, plus a swipe if your terminal supports it. Then practice a void and a refund, check that receipts print or send correctly, and confirm the tests show up in your reporting. Field teams should run at least one test where the terminal will actually be used, such as a job site or the far end of your lot, not only at the office.
7. Train Your Team and Set an End-of-Day Routine
Make sure everyone who uses the terminal knows how to run a sale, void a transaction, issue a refund, and handle a decline. Remind them never to write down card numbers. For field teams, agree on who carries which device, where devices are charged overnight, and how each day’s batch is closed and checked against the jobs completed. A short routine keeps the office from chasing technicians for missing payments.
Common Issues and Troubleshooting Tips
Even with a careful setup, you may run into a problem now and then. Here is where to start:
- Wi-Fi will not connect: confirm the password, move closer to the router, avoid guest networks with a sign-in page, and restart the terminal.
- No cellular signal: move near a window or step outside, restart the terminal, check that the SIM card is seated, and ask your provider whether the data plan is active or the carrier has an outage.
- Transaction declines: check that the card was read or entered correctly and ask for another card. If you see declines across several different cards, contact your processor.
- Receipt printer problems: check that the paper roll is loaded the right way and that the battery has enough charge.
- Battery runs out mid-shift: keep a car charger or spare battery in each vehicle, and charge every device overnight.
Wireless Terminal or Virtual Terminal?
A wireless terminal handles in-person payments. A virtual terminal is a secure website your staff uses to enter card or ACH payments taken by phone, mail, or invoice, with no hardware beyond a computer. Many businesses use both. Learn how virtual terminal credit card processing works for Wisconsin businesses.
| Feature | Wireless Terminal | Virtual Terminal |
|---|---|---|
| Hardware | Portable payment device | None beyond a computer and internet connection |
| How payment happens | The customer taps, inserts, or swipes their card in person | Staff enters card or ACH details for the customer |
| Connection | Wi-Fi, cellular, or a paired phone | Web browser |
| Best for | Field teams, events, deliveries, and tableside payments | Phone orders, invoices, and recurring billing |
Frequently Asked Questions
How long does it take to set up a wireless credit card terminal?
Once your merchant account is approved and the terminal is ready to activate, the hands-on setup, from charging the device to running a test sale, often takes under an hour. Account approval and shipping take longer and vary by provider.
Should I choose a Wi-Fi or cellular terminal?
Choose Wi-Fi if you take payments in places with a network you control. Choose cellular if your team works on the road or at customer sites. If you do both, ask about a terminal that supports both connections.
Do I need to close a batch every day?
Closing a batch sends the day’s approved sales for settlement, which is how the money moves toward your bank account. Depending on the terminal and your processor, the batch may close automatically at a set time or someone may need to close it by hand. Find out which way yours is set up, because a batch left open can delay your deposit. Field teams should make the batch close part of the end-of-day routine.
Do I need both a wireless terminal and a virtual terminal?
Only if you take payments both in person and remotely. A wireless terminal covers in-person sales, and a virtual terminal covers phone orders, invoices, and recurring billing.
What happens if my terminal loses signal at a job site?
Some terminals offer an offline mode that stores the payment and sends it once the connection returns. It usually has to be turned on by your processor, it has limits, and a stored payment can still be declined later. If your crews often work out of signal range, talk to us about credit card processing for Wisconsin contractors and how to plan for dead zones.
Are wireless credit card terminals secure?
Current terminals are built to protect card data, and chip and contactless payments are harder to counterfeit than a magnetic stripe. Security also depends on how you use the device: keep terminals with their assigned employees, use separate logins, and never write card numbers down. Ask your provider which PCI responsibilities apply to your business.
Get a Free Statement Review
Setting up a wireless credit card terminal does not have to be complicated, and you do not have to do it alone. Motus Financial is a locally owned merchant services company based in Sun Prairie, serving businesses across Wisconsin. We help owners choose, set up, and support the right terminal for the way their team works. Send us a recent processing statement and we will review what you pay today, recommend a setup that fits your team, and tell you plainly if a simpler setup would do the job.
Get a Free Statement Review or call 608-819-8666. You can also find Motus Financial on Google Maps, or learn more about our merchant services in Wisconsin.

 Our POS systems are designed to streamline in-store transactions. With features like inventory management, sales reporting, and customer tracking, our POS solutions help you run your business more efficiently. Our terminals are compatible with various payment methods, including chip cards, contactless payments, and mobile wallets.